
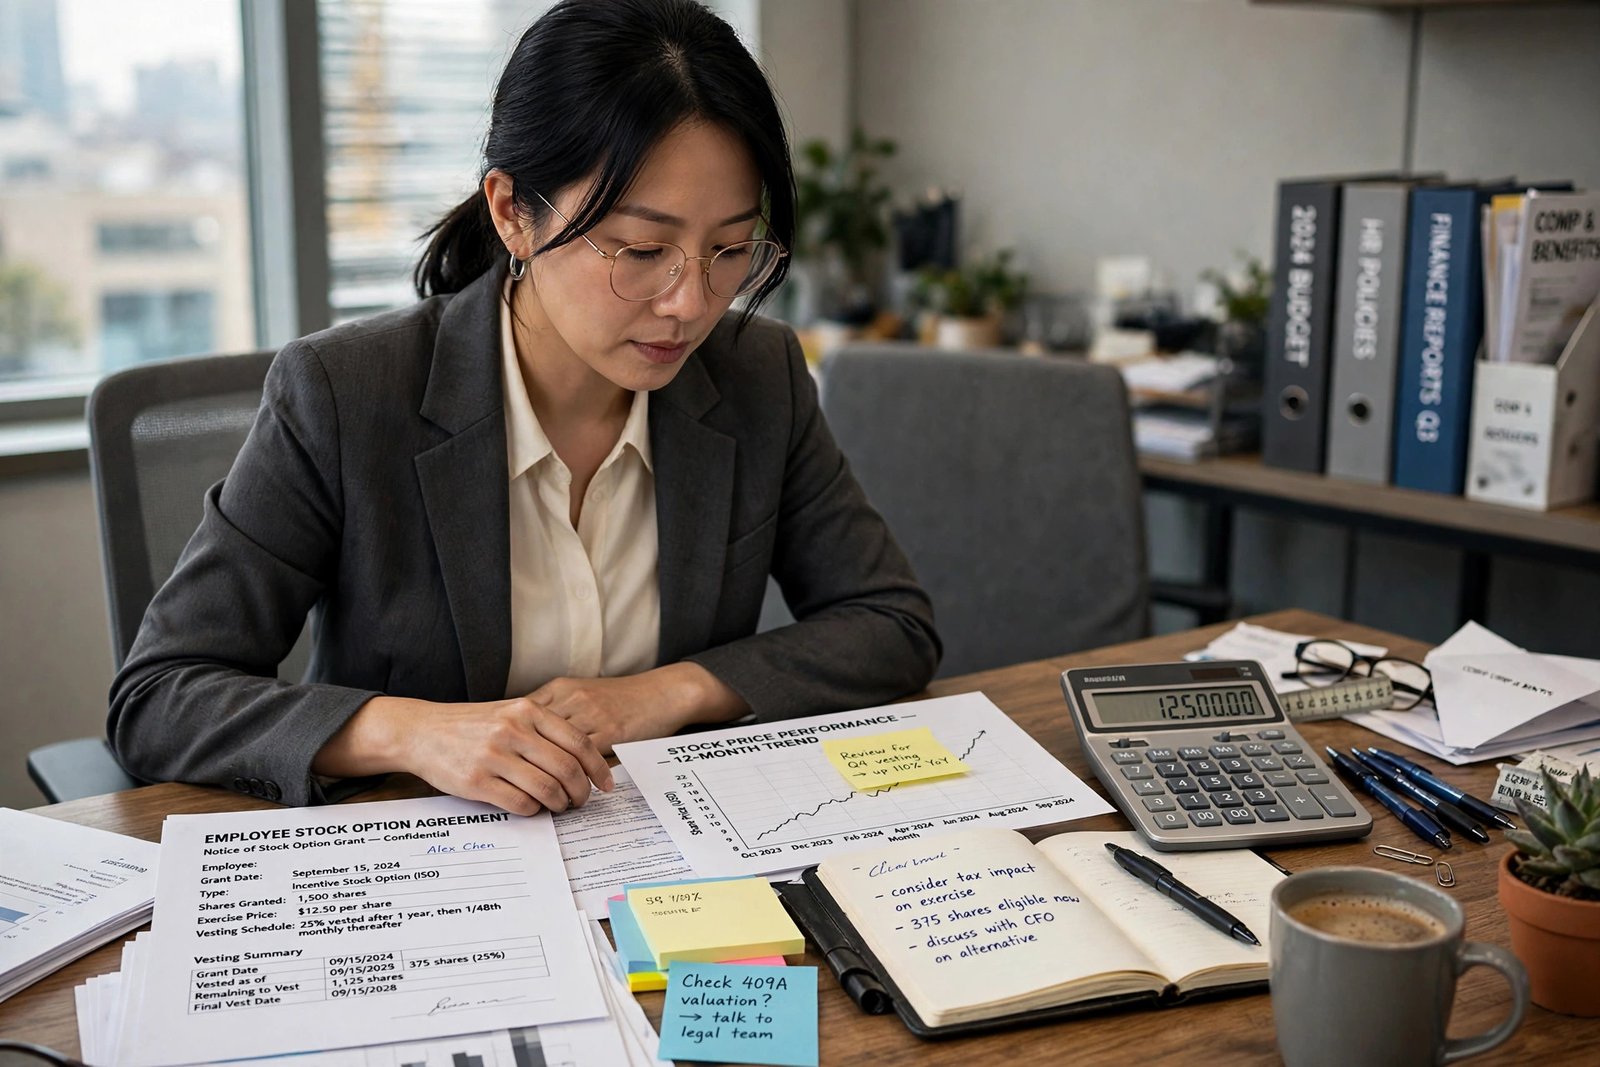
Your employee stock options could be worth life-changing money — or they could expire worthless while you agonize over timing. Every year, employees leave millions on the table through two opposite mistakes: cashing out the moment options vest and paying maximum taxes, or holding concentrated company stock until a downturn wipes out years of gains.
The right time to cash out isn't a date on the calendar — it's a function of taxes, vesting schedules, concentration risk, and your life plans. Here's the decision framework finance professionals actually use.
First, Know What You Hold: ISOs vs. NSOs vs. RSUs
Incentive Stock Options (ISOs) get special tax treatment: no regular income tax at exercise (though AMT may apply), and if you hold the shares 2+ years from grant and 1+ year from exercise, gains qualify for long-term capital gains rates. Non-Qualified Stock Options (NSOs) are simpler but harsher — the spread at exercise is taxed as ordinary income immediately. RSUs aren't options at all; they're shares delivered at vesting, taxed as income on delivery.
This distinction drives everything. With ISOs, early exercise plus the holding periods can convert ordinary income into capital gains — potentially saving 15–20% in taxes. With NSOs, there's rarely a tax benefit to waiting, so the decision is purely about investment merit. Pull up your grant agreements and equity portal before making any move; acting on the wrong assumption about your grant type is the most expensive mistake in this whole process.
The Concentration Rule: Never Let One Stock Run Your Life
Financial planners use a bright line: no single stock — including your employer's — should exceed 10–15% of your net worth. Above that, you're not investing; you're making a leveraged bet on one company with both your paycheck and your portfolio riding on it. Enron and Lehman employees learned this lesson catastrophically; startup employees learn it every downturn.
Do the math honestly: add unvested equity at current fair value to your vested holdings. If the total exceeds 15% of your net worth, you have a concentration problem regardless of how much you believe in the company. The fix is systematic selling — many advisors recommend selling RSUs at vesting and trimming options on a schedule, treating equity compensation as cash compensation that happens to arrive as stock. Your loyalty to your employer and your portfolio construction are separate decisions.
For the authoritative take, visit IRS guidance on stock options taxation.
Tax Timing: The Windows That Save Real Money
For NSOs and RSUs, timing sales into lower-income years (a sabbatical, grad school, early retirement) can cut your marginal rate significantly. For ISOs, the qualifying disposition holding periods are the main lever — but watch the AMT trap: exercising large ISO blocks can trigger alternative minimum tax even though no regular tax is due, creating a cash tax bill on paper gains. Model AMT before exercising, not after.
Year-end bunching matters too. If you're near a tax bracket threshold, splitting exercises across December and January can keep you in a lower bracket. And if you're leaving the company, know your post-termination exercise window — the standard 90 days for ISOs is brutally short, though many startups now extend it to 2–10 years. Letting options expire unexercised after departure is heartbreakingly common; calendar the deadline the day you resign.
Life Events Beat Market Timing
The best reasons to cash out have nothing to do with the stock chart: a home down payment, paying off high-interest debt, funding a career break, diversifying before a major life change. Money has a job to do, and equity sitting in one volatile stock isn't doing it. If selling a chunk funds a goal that compounds in life value — like buying in a market you otherwise couldn't enter — that's a win regardless of what the stock does next.
Conversely, the worst reason to hold is inertia dressed up as optimism. 'I'll sell when it hits X' without a written plan is how people ride stocks up and back down. Write your sell rules in advance: price targets, percentage trims per quarter, or life-event triggers. Then execute mechanically. The employees who build real wealth from equity comp aren't the best stock-pickers — they're the ones with a written plan they actually follow.
The Exercise-and-Hold Decision for Pre-IPO Options
If your company is still private, exercising early (including 83(b) elections within 30 days of early exercise) can start the long-term capital gains clock ticking while the 409A valuation is low — potentially converting a future fortune from ordinary income to capital gains. This is the highest-leverage tax move in startup equity, and the 30-day 83(b) deadline is unforgiving: miss it and the benefit evaporates permanently.
But early exercise means paying cash for illiquid shares in a company that may fail — only do it with money you can lose, and only after diligence on the company's prospects. Get the 409A valuation, understand the liquidation preferences ahead of common stock, and consider: would you invest this cash in this company if you didn't work there? If the honest answer is no, don't let the tax tail wag the investment dog.
You can verify the details at SEC on exercising stock options.
Coordinating Equity with Your Broader Financial Plan
Stock options don't exist in isolation — they're one piece of a portfolio that includes your 401(k), emergency fund, and life goals. The coordination mistakes are common: employees max out company stock while neglecting 401(k) diversification, or they exercise options without reserving cash for the tax bill (the AMT surprise has forced fire sales of the very shares people exercised to keep). Model the full cash flow of any exercise — cost plus taxes — before committing.
Sequence your moves deliberately: fund the 401(k) match first (free money), maintain the emergency fund (never raid it to exercise), then handle equity. If you're considering leaving, the decision tree starts months before your last day — understand your exercise window, the cost to exercise everything vested, and whether early-exercise plus 83(b) makes sense while still employed. And coordinate with major life events: exercising into a year you'll also sell a house or realize other gains can stack you into higher brackets unnecessarily. Your equity comp, tax plan, and life calendar should be one conversation, ideally with a CPA or planner who specializes in equity compensation.
Keep exploring with how taxes work for self-employed income and saving before quitting to freelance.
When should you cash out employee stock options? When concentration exceeds 10–15% of your net worth, when the tax timing is favorable, when a life goal needs funding — and always according to a written plan, not a gut feeling. Know your grant type, model the taxes before you act, calendar your post-termination deadlines, and treat equity as compensation to be harvested, not a lottery ticket to be hoarded. The goal isn't perfect timing; it's capturing real wealth from work you already did.
Frequently Asked Questions
Should I exercise stock options before leaving a company?
Usually yes, if they're in the money — most companies give only 90 days post-termination to exercise ISOs before they expire. Check whether your company extended the window, and model the cost plus taxes before your last day.
What is the 83(b) election for stock options?
A tax filing (due within 30 days of early exercise) that lets you pay tax on the current low value of unvested shares rather than their higher value at each vesting date. Miss the 30-day deadline and you lose the benefit permanently.
Are employee stock options taxed twice?
It can feel that way: NSO spreads are taxed as income at exercise, then further gains as capital gains at sale. ISOs avoid the first tax if you meet holding periods, but AMT may apply. Proper planning avoids paying more than required.
How much of my net worth should be in company stock?
Most planners cap it at 10–15%. Remember your salary already depends on the company — doubling down with your investments concentrates risk precisely where you can least afford it.