How Do I Write a Simple Business Plan for a Small Shop?

How do I write a simple business plan for a small shop? Forget the 40-page documents business schools assign — nobody reads those, including the person who wrote them. What you need is a plan that’s short enough to actually use and complete enough to catch bad ideas before they cost money.
I’ve written plans that raised money and plans that saved me from terrible ideas — the second kind was more valuable. Here’s the lean version that does both jobs.
How Do I Write a Simple Business Plan for a Small Shop? Start With One Page
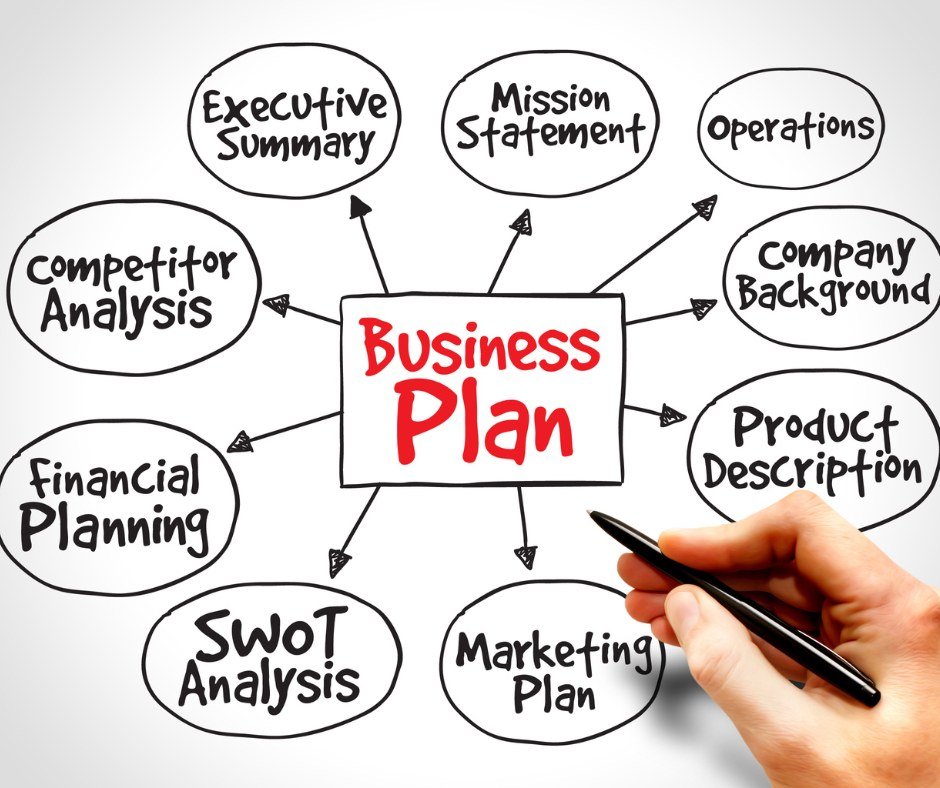
The one-page plan forces clarity. Nine boxes: what you sell, who buys it, why they’ll choose you over alternatives, how you’ll reach them, what it costs to run, what you’ll charge, how much you’ll sell, what could kill you, and what success looks like in year one. If you can’t fit it on one page, you don’t understand the business yet — and that’s the point of the exercise.
This isn’t dumbing down; it’s the discipline. A coffee shop plan that says ‘customers: everyone’ is a plan to fail — ‘remote workers within 10 blocks who need morning coffee and afternoon workspace’ is a plan you can execute. Write the one-pager first, argue with it for a week, and only then expand the sections that need detail. The SBA’s business-plan tool at the U.S. Small Business Administration offers templates when you’re ready to flesh it out.
The Numbers: Costs, Prices, and Break-Even
Every small-shop plan lives or dies on three numbers. Startup costs: buildout, equipment, inventory, deposits, licenses, and 3–6 months of operating cushion — be brutally honest here; underestimating startup costs is the number one plan-killer. Monthly burn: rent, payroll, inventory restock, utilities, insurance, loan payments. Break-even: monthly burn divided by average gross profit per sale = sales needed per month.
Example: $8,000 monthly burn, $12 average profit per customer = 667 customers a month, or ~22 a day. Now ask: can this location plausibly deliver 22 paying customers daily? If the math says no, no amount of passion fixes it — and discovering that on paper instead of after signing a lease is exactly what the plan is for. For pricing your products to actually profit, pair this with How do I price my handmade products to actually make a profit.
What Banks and Landlords Actually Read
If you need funding or a lease, expand three sections: the financial projections (12-month cash flow, not just profit — banks know profit without cash flow is fiction), your personal investment (lenders want to see your own money at risk, typically 15–30% of the total), and your experience (why you, specifically, can run this shop).
Keep the whole document under 15 pages. Bankers skim; lead with an executive summary that states the ask (‘seeking $80,000 loan for…’), the numbers, and the repayment plan in the first two pages. Landlords care about one thing: can you pay rent for the full lease term? Show the cushion. Everything else is supporting detail.
Your small-shop plan checklist:
- One-page version first: product, customer, edge, channels, costs, price, volume, risks, goal.
- Calculate startup costs honestly, monthly burn, and break-even customer count.
- For funding: 12-month cash flow, your own investment, and your relevant experience up front.
- Write the risks section — it’s what serious readers trust most.
- Set kill criteria now; review the plan quarterly, not never.
The Section Everyone Skips (Don’t)
Risks and mitigations — the part founders hate writing and readers trust most. List the three things most likely to hurt you (a competitor opens nearby, foot traffic disappoints, your key supplier raises prices) and one concrete response for each. This isn’t pessimism; it’s the section that proves you’re a serious operator rather than a dreamer.
Then define your kill criteria in advance: ‘If we’re not at X revenue by month 9, we pivot to Y / close.’ Deciding this now, while you’re rational, beats deciding it later while you’re emotionally invested and broke. The best business plans aren’t predictions — they’re decision frameworks. Revisit yours quarterly; a plan you never reread is just a homework assignment.
The Bottom Line
How Do I Write a Simple Business Plan for a Small Shop? Pro Tips
Pro tip: write the financial section first, not last. Most people write the inspiring vision pages, then discover the numbers don’t work on page 30 — after they’re emotionally committed. Start with startup costs, monthly burn, and break-even math; if the numbers work, the rest of the plan is worth writing. If they don’t, you’ve saved weeks of work and possibly your savings. Numbers first is the professional order.
Also: get a second pair of eyes specifically tasked with killing the idea. Ask a skeptical friend or a SCORE mentor (free) to attack the plan’s assumptions — foot traffic estimates, pricing, competition. You want the holes found now, by someone kind, rather than later, by the market, which is never kind. The plans that survive hostile review are the ones worth funding. And keep the plan alive: a quarterly 30-minute review against actuals turns the document from homework into a management tool.
Validate the core assumptions before you write a single page — the plan documents your thinking, but the thinking has to come from reality, not optimism. Talk to potential customers, mystery-shop competitors, verify foot-traffic claims by actually counting passersby at different hours. Every hour of validation saves ten hours of planning based on fantasy. The best business plans aren’t written; they’re researched, and the writing is just the recording. Research first, write second, and let reality edit your assumptions.
A useful small-shop business plan fits on one page, centers on honest numbers (startup costs, monthly burn, break-even), and includes the risks you’d rather not think about. Write it to find the flaws before they cost money, expand it only as much as your audience needs, and revisit it quarterly. The plan isn’t the business — but it’s the cheapest way to test-drive one.
A business plan’s job is to find the flaws cheaply — on paper instead of with your lease deposit. Numbers first, hostile review second, quarterly revisits after. The plan that survives that process isn’t just a document; it’s a tested thesis about a business that can actually work.